The Last Advance
The publisher was always a fund. What happens when there is nothing left to finance?
TAM-UOO.01 · The Unit of One · The Approximate Mind
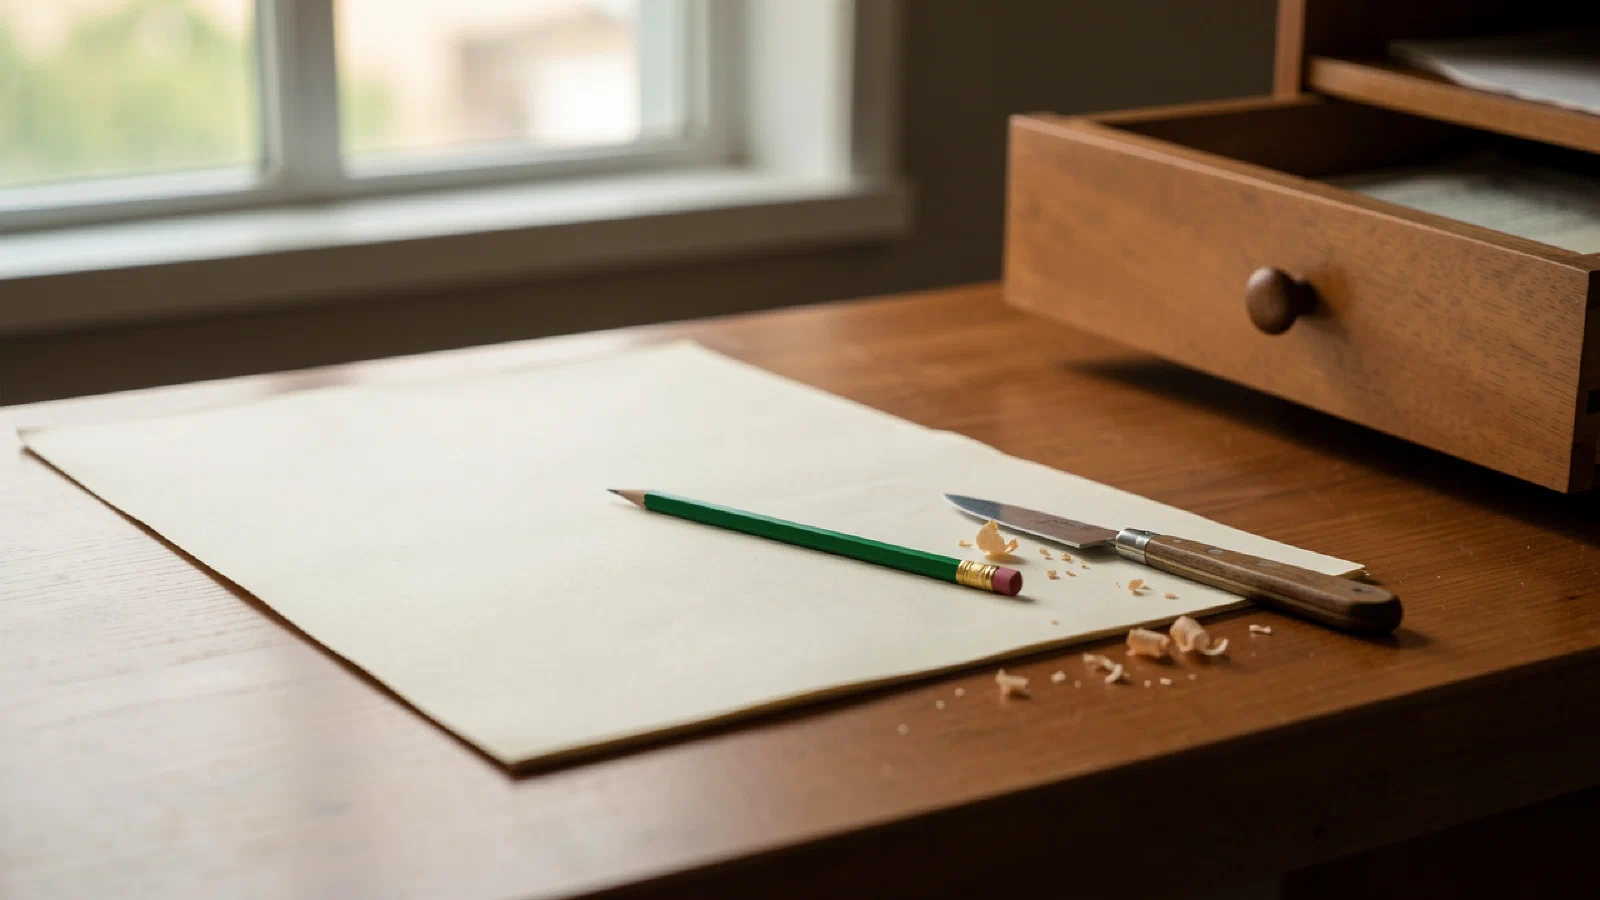
Ruth Halloran has worked at the same publishing house for thirty-one years, and she still reads submissions on paper, marking them with a green pencil her first boss gave her in 1995. She sharpens it with a paring knife, never a sharpener. The pencil is shorter now than her thumb.
On a Tuesday in March she sits in the quarterly acquisitions meeting and argues for a first novel by a poet from Duluth. The room runs the numbers the way the room has always run the numbers. Advance against royalties. Print run. Marketing allocation. Comparable titles and what they earned. The finance director asks the question the finance director always asks: what does the portfolio look like if this one fails?
Ruth has heard the question a thousand times. It has never once been about the book.
The Costume#
We talk about publishers, labels, and studios as if they were in the business of books, music, and films. They are not, or not primarily. Strip away the cultural costume and what remains is a specific financial machine: an institution that commits capital before demand reveals itself.
The advance is the machine’s beating heart. A publisher pays an author for a book that does not yet exist, to be sold to readers who have not yet asked for it. A label fronts the studio time, the production, the promotion, for a record nobody has heard. A studio greenlights two hundred million dollars against an opening weekend three years away. In every case the money moves first and the demand answers later, if it answers at all.
This is venture capital. It has always been venture capital. The portfolio logic is identical: most positions fail, a few return modestly, and one hit pays for everything. The industry’s own folklore admits it. One book in ten earns out its advance. One single carries the label’s quarter. William Goldman compressed four decades of Hollywood into three words: nobody knows anything.
The label was never in the music business. It was in the risk business.
Once you see the costume, the institution’s strangest features stop being strange. Recoupment, the practice of charging the artist’s earnings against the money spent making the work, is not greed in the first instance. It is how a fund recovers its basis. Ownership of masters is not theft in the first instance. It is the equity a financier takes for bearing a loss the artist could not bear alone. The greenlight committee, the acquisitions board, the A&R department: these are investment committees, and their cruelty and their caution both follow from the arithmetic of a portfolio where ninety percent of the capital is going to die.
The whole apparatus rests on two facts holding at once. Production is expensive. Outcomes are unknowable. Remove either fact and the apparatus has no reason to exist.
The Quiet Removal#
AI is removing the first fact, and it is not doing it the way industries usually lose their footing.
The cost of producing a finished, professional-grade creative work is falling toward the cost of the conversation that specifies it. A song that required a studio, an engineer, and session musicians now requires an afternoon. A book that required a year of supported labor can be drafted, in some forms, in a week. The floor is not zero, and we will come back to what does not fall. But the production budget, the number the advance existed to cover, is collapsing across category after category.
Watch what this does to the financing function. It does not get outcompeted. It does not get disrupted by a leaner rival doing the same job for less. It becomes unnecessary, which is a different and more complete kind of ending. There is no advance because there is nothing to advance against. There is no recoupment because there is no basis to recover. There are no masters to own because the capital that purchased ownership was never deployed. The portfolio does not lose to a better portfolio. It dissolves because the risk it pooled has stopped existing.
Nothing disappears faster than a function nobody needs to attack.
Most institutional endings are fights. This one is an evaporation. The publisher’s other functions, the selection, the distribution, the audience, will be contested ground for years, fought over by platforms and algorithms and whatever replaces the marketing department. But the financial heart, the oldest part, the part the whole org chart grew around, simply stops being asked for. A fund with nothing to finance is not a smaller fund. It is a building with the lights on.
What the Advance Also Was#
The advance was never only a financial instrument, and what dissolves with it is not only risk.
The advance was a wage. It bought the year. The poet from Duluth, if Ruth wins the room, will receive a sum that is officially a bet against future royalties and is actually twelve months of rent, groceries, and mornings in which she does not have to do anything but write. Every advance in every creative industry has carried this second cargo: patronage smuggled inside a financial transaction, the artist’s time purchased under the accounting fiction that it was the artist’s output being purchased.
Production got cheap. The year did not.
The cost that AI collapses is the cost of making the artifact. The cost it does not touch is the cost of a human life spent attending to something long enough to have something to say about it. The novel that takes a week to draft and a year to mean something still requires the year. When the advance dissolves, the artifact’s financing goes with it, and the year’s financing goes with it too, and nothing in the new arrangement is designed to notice the difference.
This is the void the dissolution opens. Not a shortage of works. There will be more works than any civilization has ever produced. A shortage of funded attention: of people paid, in the old accidental way, to spend a long time becoming the person who could make a particular thing.
The Surviving Portfolio#
The dissolution is not uniform, and honesty requires the map.
At the top of the cost curve, the portfolio survives. A film that requires physical sets, location logistics, a thousand crew members, and a global marketing campaign still requires capital committed before demand reveals itself, and so the studio persists there, in its oldest form, financing spectacle. The same holds wherever the work’s value is inseparable from expensive physical reality: the stadium tour, the prestige television production, the architectural monument. Where production stays costly, the fund stays necessary.
So the institution does not die everywhere at once. It retreats upward. The label keeps its superstars and loses its midlist. The publisher keeps its franchises and loses its first novels. The studio keeps its tentpoles and loses everything that used to be called the middle of the slate. The portfolio concentrates at the only altitude where portfolios still make sense, and the vast territory below it, the territory where most artists actually lived, definances.
The fund does not collapse. It retreats to the only ground that still needs it, and the ground it leaves behind is most of the map.
The abandoned ground is not empty. It is being settled by something with a different shape: production without financiers, demand that speaks before supply commits, firms organized around a person rather than a portfolio.
But a loss should be named before the settlement is celebrated. The portfolio, for all its cruelty, did one thing no demand-driven system has yet proven it can do: it paid for the gamble. It put real money behind work that no existing audience had asked for, because the arithmetic of one-in-ten required swinging at things that looked impossible. Some fraction of everything we now call essential was, at the moment of its financing, a position in somebody’s losing column. I wonder whether the unasked-for book still gets written when no one is left to lose money on it.
The Pencil#
The acquisitions meeting ends without a decision, which Ruth has learned means no. She walks back to her office and puts the poet’s manuscript in the drawer where the maybes go, and takes out the paring knife, and sharpens the green pencil, although it does not need it.
The pencil was a gift from a man who rejected eleven thousand manuscripts in his career and was proud of perhaps forty books. He told her once that the job was not finding the good ones. Anyone can admire. The job was saying no a thousand times in a row without going numb, so that the yes, when it came, still meant something.
The checkbook is leaving the building. The advance, the portfolio, the recoupment ledger, the whole financial machine that made the green pencil’s verdicts consequential: all of it is dissolving into a world where the poet from Duluth can publish tomorrow, by herself, for nothing.
The pencil never financed anything. It only judged. And judgment, unlike capital, is not made unnecessary by cheap production. It may be the only part of Ruth’s institution that the dissolution makes more valuable, and it is the one part that was never on the balance sheet.
She holds it up to the window. Shorter than her thumb. Still writes.
This is the first essay in The Unit of One, a five-essay series of The Approximate Mind examining the firm that emerges when the cost of knowing each customer collapses. The Arbitrage series mapped where AI dissolves the spreads of the averaged economy. This series asks what gets built on the ground the dissolution clears. This essay traces the quiet end of the portfolio: the financing function at the heart of publishers, labels, and studios, which dissolves not because something beats it but because the risk it pooled stops existing. The second essay, “The Sale That Tests,” follows the inversion that replaces it: demand that speaks before production commits.
References#
The Economics of Creative Industries
Caves, Richard E. Creative Industries: Contracts between Art and Commerce. Harvard University Press, 2000.
De Vany, Arthur. Hollywood Economics: How Extreme Uncertainty Shapes the Film Industry. Routledge, 2004.
Elberse, Anita. Blockbusters: Hit-making, Risk-taking, and the Big Business of Entertainment. Henry Holt, 2013.
Goldman, William. Adventures in the Screen Trade. Warner Books, 1983.
Publishing and Music as Financial Institutions
Passman, Donald S. All You Need to Know About the Music Business. 10th ed., Simon & Schuster, 2019.
Thompson, John B. Merchants of Culture: The Publishing Business in the Twenty-First Century. Polity Press, 2010.
Risk, Uncertainty, and the Portfolio
Knight, Frank H. Risk, Uncertainty and Profit. Houghton Mifflin, 1921.
Baumol, William J., and William G. Bowen. Performing Arts: The Economic Dilemma. Twentieth Century Fund, 1966.
The Long Tail and the Definanced Middle
Anderson, Chris. The Long Tail: Why the Future of Business Is Selling Less of More. Hyperion, 2006.
Series Anchors
The Approximate Mind, TAM-033 (The Curation Economy): value moving from capturing attention to structuring understanding.
The Approximate Mind, TAM-ARB.13 (Melting Ice): businesses sitting on dissolving spreads as depreciating positions.
The Approximate Mind, TAM-RIM.6-03 (The Inverted Firm): the firm reorganized after coordination cost collapses.
How this essay connects to others across The Approximate Mind.